CGT Changes Australia 2027: What Small Business Owners Need to Know
The CGT Changes Australia 2027 reforms are set to change how capital gains are taxed in Australia from 1 July 2027. These changes are particularly important for business owners, investors, individuals, trusts and partnerships who may sell assets or realise capital gains in the future.
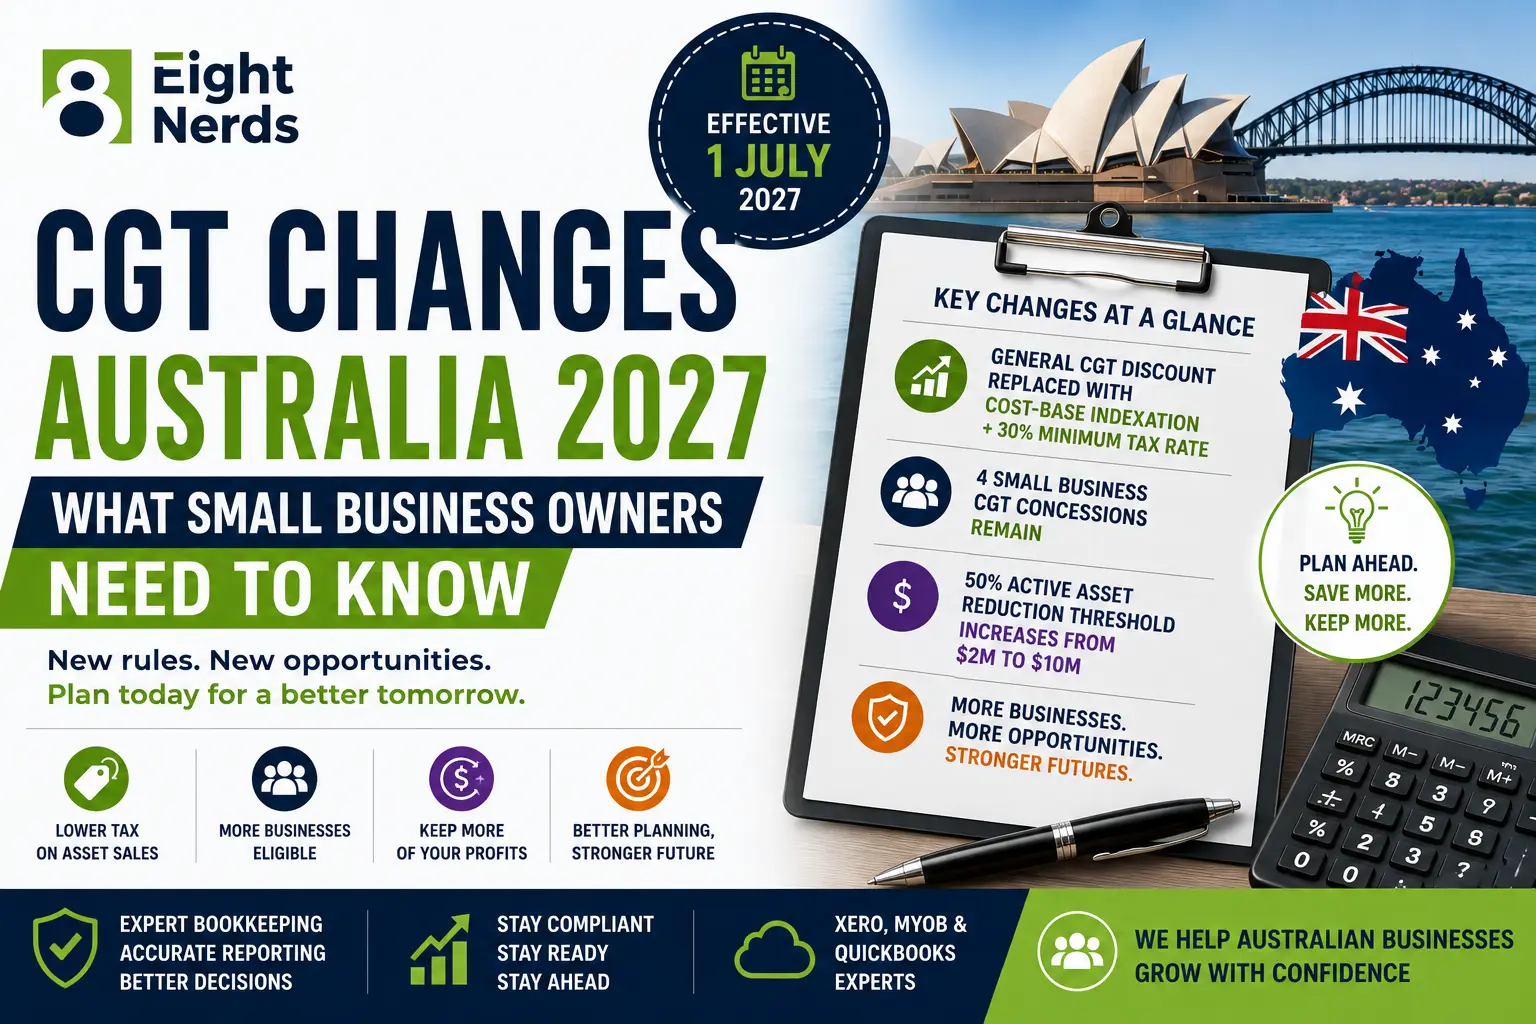
For small business owners, however, there is an important piece of good news: the Australian Government has confirmed that the four existing small business Capital Gains Tax (CGT) concessions will remain available for eligible businesses. In addition, the turnover threshold for the 50% active asset reduction is increasing from $2 million to $10 million from 1 July 2027.
At the same time, broader CGT rules are changing. From 1 July 2027, the existing 50% CGT discount for individuals, trusts and partnerships will be replaced by a system based on cost-base indexation, together with a 30% minimum tax rate on real capital gains. The legislation implementing these changes received Royal Assent on 26 June 2026.
For Australian business owners, understanding these changes early can help with business planning, asset sales, restructuring and long-term financial decisions.
What Are the CGT Changes Australia 2027?
The CGT Changes Australia 2027 reforms introduce a new approach to taxing capital gains for individuals, trusts and partnerships.
From 1 July 2027, the current 50% CGT discount will be replaced by cost-base indexation for relevant assets held for more than 12 months. A minimum tax rate of 30% will also apply to relevant real capital gains.
The basic idea is to adjust the cost base of an asset for inflation before calculating the taxable capital gain.
This means the tax system will focus more closely on the real increase in an asset’s value after inflation, rather than simply applying a flat 50% discount to the capital gain.
However, the reforms do not simply remove CGT concessions for small businesses.
The Government has specifically confirmed that the four existing small business CGT concessions will remain, allowing eligible businesses to potentially reduce, defer or eliminate CGT on qualifying active business assets.
When Do the CGT Changes Start in Australia?
The CGT Changes Australia 2027 will apply from 1 July 2027.
This date is important because the reforms are prospective. They are not designed to retrospectively change the tax treatment of capital gains that accrued before the start date.
Under the new rules, gains that accrue before 1 July 2027 retain the existing treatment, while the new system applies to capital gains accruing from 1 July 2027.
For business owners, this means the timing of an asset sale or other CGT event can become an important planning consideration.
However, businesses should not make a major commercial decision purely because of the tax change. The financial, operational and commercial circumstances of the transaction should also be considered.
What Is Changing for Small Business CGT Concessions?
One of the most important aspects of the CGT Changes Australia 2027 is that the four existing small business CGT concessions are staying.
These concessions can help eligible small businesses reduce or eliminate CGT when they dispose of qualifying active business assets.
The four main concessions are:
- 15-year exemption
- 50% active asset reduction
- Small business retirement exemption
- Small business rollover
The concessions have different eligibility requirements, so a business cannot automatically assume that it qualifies for all four.
The Government has confirmed that the concessions will continue and that the turnover threshold for the 50% active asset reduction will increase significantly.
What Is the New $10 Million CGT Turnover Threshold?
The increase from $2 million to $10 million is one of the biggest changes for small businesses under the CGT Changes Australia 2027 reforms.
Currently, the small business CGT concessions have a $2 million aggregated turnover threshold as part of their eligibility framework.
From 1 July 2027, the turnover threshold for the 50% active asset reduction will increase to $10 million.
This means more Australian businesses may be able to access the 50% active asset reduction if they meet the other eligibility conditions.
It is important to understand that the $10 million threshold does not mean every business with turnover below $10 million automatically qualifies for every small business CGT concession.
Each concession has its own conditions.
For example, the rules can consider factors such as:
- Aggregated turnover
- Whether the asset is an active asset
- How long the asset has been held
- Whether the asset is connected with the business
- The owner’s circumstances
- The type of CGT event
- Other eligibility requirements
Professional tax advice should therefore be obtained before relying on a CGT concession.
What Is the 50% Active Asset Reduction?
The 50% active asset reduction is one of the key small business CGT concessions affected by the new threshold.
If an eligible small business disposes of a qualifying active asset, the concession can potentially reduce the capital gain by 50%.
An active asset can include certain assets used in carrying on a business, subject to the specific requirements in the tax law.
For example, imagine an Australian business sells a qualifying business asset and calculates a capital gain of $400,000.
If the business meets the relevant requirements for the 50% active asset reduction, the capital gain may potentially be reduced by 50% before considering other applicable CGT concessions and tax rules.
The actual outcome depends on the business’s circumstances and the type of asset involved.
Who Can Benefit From the CGT Changes Australia 2027?
The CGT Changes Australia 2027 may be particularly relevant to Australian small business owners who are considering selling, restructuring or transferring business assets.
Potentially affected businesses include:
- Professional services businesses
- Retail businesses
- Construction businesses
- Manufacturing businesses
- Trades and contractors
- Technology businesses
- Family-owned businesses
- Hospitality businesses
- Agricultural and primary production businesses
- Other Australian businesses that own qualifying active assets
The Government estimates that all 2.7 million active small businesses will be eligible for the 50% active asset reduction under the expanded threshold, while more than 90% of active businesses are eligible for all four existing concessions.
That does not mean every business will receive a CGT exemption. It means the broader eligibility framework creates the potential for more small businesses to access the concession when the relevant requirements are satisfied.
Do the CGT Changes Australia 2027 Affect Existing Business Assets?
This is one of the most important questions for business owners.
The reforms are prospective, meaning the new CGT arrangements are designed to apply to gains accruing from 1 July 2027 rather than retrospectively changing gains that arose before that date.
Treasury’s small business explainer states that business value built up before 1 July 2027 retains the old 50% discount treatment, regardless of when the business is eventually sold, subject to the relevant rules.
This transition approach is particularly important for businesses that have accumulated significant value over many years.
It also means that businesses should maintain good records showing the history and cost base of significant assets.
How Will CGT Changes Affect Selling a Business?
Selling a business can involve multiple CGT assets and different tax considerations.
A business sale may involve:
- Goodwill
- Business premises
- Equipment
- Vehicles
- Intellectual property
- Shares
- Other business assets
The CGT treatment of each asset can vary.
Eligible small businesses may be able to access the existing small business CGT concessions when selling qualifying active business assets.
The CGT Changes Australia 2027 therefore do not mean that every business sale will suddenly be taxed under a completely different system.
Instead, the overall CGT framework is changing while the specific small business concessions are being retained and, in the case of the active asset reduction threshold, expanded.
What Is the Difference Between CGT Discount and Small Business CGT Concessions?
These two concepts are often confused.
The CGT discount is a general tax treatment that has historically allowed eligible individuals and certain other taxpayers to reduce a capital gain by 50% when an asset has been held for more than 12 months.
The small business CGT concessions are separate concessions designed specifically for eligible small businesses.
Under the CGT Changes Australia 2027, the general 50% CGT discount for individuals, trusts and partnerships is being replaced with cost-base indexation and a 30% minimum tax rate on relevant real capital gains. However, the four small business CGT concessions remain.
This distinction is critical for business owners.
A business owner should not assume:
“The 50% CGT discount is changing, so my small business CGT concession is disappearing.”
That is not the position.
The four small business concessions are staying.
How Can Bookkeeping Help With CGT Changes Australia 2027?
Good bookkeeping is an important part of preparing for CGT Changes Australia 2027, especially when a business owns significant assets.
CGT calculations can depend on the asset’s cost base, acquisition costs, improvement costs, ownership history, disposal proceeds and other information.
Businesses should therefore maintain accurate records for:
- Asset purchase dates
- Purchase prices
- Legal and professional costs
- Improvement costs
- Depreciation information
- Asset disposal dates
- Sale proceeds
- Ownership information
- Business-use records
- Supporting invoices
- Financial statements
Accounting platforms such as Xero, MYOB and QuickBooks can help businesses maintain organised financial records, but the correct tax treatment still needs to be determined based on the relevant tax rules.
Keeping records organised well before a business sale can make it easier for an accountant or tax adviser to calculate the capital gain correctly.
What Should Australian Businesses Do Before 1 July 2027?
Business owners should not wait until the last minute to understand how the CGT Changes Australia 2027 may affect them.
A practical preparation process could include:
1. Review Your Business Assets
Create a list of major assets owned by the business and identify which assets may potentially create a capital gain.
2. Check Your Records
Make sure purchase documents, improvement costs, legal expenses and other relevant records are available.
3. Understand Your Business Structure
CGT treatment can differ depending on whether the business operates through a company, trust, partnership or individual structure.
4. Review Potential Business Sales
If you are considering selling your business, discuss the timing and tax implications with a qualified tax professional well in advance.
5. Review Small Business CGT Eligibility
Do not assume that turnover alone determines eligibility. The relevant conditions for each concession should be reviewed.
6. Keep Bookkeeping Up to Date
Accurate financial records provide the foundation for better tax planning and reporting.
How Eight Nerds Can Support Australian Businesses
At Eight Nerds, we help Australian businesses maintain accurate and organised financial records using Xero, MYOB and QuickBooks.
While CGT advice and tax planning should be handled by a qualified tax professional, accurate bookkeeping provides the financial information those professionals need to assess a business’s position.
Our bookkeeping support can include:
- Transaction recording
- Bank reconciliation
- Asset record management
- Accounts payable
- Accounts receivable
- Expense categorisation
- Financial reporting
- Payroll-related bookkeeping
- GST record management
- BAS preparation support
- Xero bookkeeping
- MYOB bookkeeping
- QuickBooks bookkeeping
As a Xero Certified Advisor, Eight Nerds helps Australian businesses maintain structured cloud accounting records and improve financial visibility.
For business owners preparing for the CGT Changes Australia 2027, having organised asset and financial records can make discussions with accountants and tax advisers more efficient.
Frequently Asked Questions About CGT Changes Australia 2027
What are the CGT Changes Australia 2027?
From 1 July 2027, the general 50% CGT discount for individuals, trusts and partnerships will be replaced by cost-base indexation and a 30% minimum tax rate on relevant real capital gains. The four existing small business CGT concessions will remain.
When do the CGT changes start in Australia?
The main changes commence from 1 July 2027. The legislation implementing the general CGT reforms received Royal Assent on 26 June 2026.
Is the 50% CGT discount being removed for small businesses?
The general 50% CGT discount for individuals, trusts and partnerships is changing. However, the 50% active asset reduction under the small business CGT concessions is staying, subject to eligibility requirements.
What is the new $10 million CGT threshold?
From 1 July 2027, the turnover threshold for the small business 50% active asset reduction increases from $2 million to $10 million. Other eligibility conditions still apply.
Does every business under $10 million turnover qualify for the CGT concessions?
No. The $10 million threshold is only one part of the eligibility framework for the relevant concession. Businesses must satisfy the other requirements of the applicable small business CGT concession.
Are the four small business CGT concessions being removed?
No. The Australian Government has confirmed that the four existing small business CGT concessions will remain.
What are the four small business CGT concessions?
The four concessions are the 15-year exemption, 50% active asset reduction, small business retirement exemption, and small business rollover.
Will assets purchased before 1 July 2027 be affected?
The reforms are prospective. Gains accruing before 1 July 2027 retain the existing treatment, subject to the applicable transitional rules.
Should I sell my business before 1 July 2027?
There is no universal answer. The decision should depend on the business’s commercial circumstances, expected sale price, asset structure, available concessions, ownership structure and tax position. A qualified tax adviser should assess the specific situation before a major transaction is made.
How does bookkeeping affect CGT?
Accurate bookkeeping helps maintain records of asset purchases, improvements, expenses, sales and other information that may be relevant when calculating a capital gain or assessing a CGT concession.
Does CGT apply when selling a business in Australia?
A sale of a business can trigger CGT depending on the assets involved and the circumstances of the transaction. Eligible small businesses may be able to access one or more CGT concessions.
CGT Changes Australia 2027
The CGT Changes Australia 2027 reforms represent a significant change to Australia’s capital gains tax system, but small business owners should not assume that all CGT concessions are disappearing.
The Australian Government has confirmed that the four small business CGT concessions will remain, while the turnover threshold for the 50% active asset reduction will increase from $2 million to $10 million from 1 July 2027.
At the same time, the general CGT framework for individuals, trusts and partnerships is changing from 1 July 2027, with cost-base indexation replacing the existing 50% discount and a 30% minimum tax rate applying to relevant real capital gains. These changes have already been legislated.
For Australian business owners, the most practical step is to start preparing early. Review your business structure, identify significant assets, maintain accurate records, understand the small business CGT concessions and discuss potential transactions with a qualified tax professional.
Accurate bookkeeping also plays an important supporting role. With organised records in Xero, MYOB or QuickBooks, businesses can provide their accountants and tax advisers with clearer financial information when assessing CGT and other tax obligations.
At Eight Nerds, we support Australian businesses with professional bookkeeping, financial reporting, BAS support, payroll-related bookkeeping and cloud accounting services. Our goal is to help businesses keep their financial records organised so they can make informed decisions and work more efficiently with their tax and accounting professionals.
This article provides general information about CGT Changes Australia 2027 and is not individual tax advice. CGT treatment depends on the business structure, asset, transaction, and individual circumstances. Businesses should consult a registered tax agent or qualified tax professional before making decisions about the timing or structure of an asset or business sale.
All Categories
Recent Posts
Sydney’s Top Bookkeeping Agency | Complete Guide for Australian Businesses
What Does a Top Bookkeeping Firm in Australia Actually Do?
Monthly PAYG Instalments in Australia: What Businesses Need to Know in 2026