Business Profitability Analysis for Growing Australian Businesses | Eight Nerds
Growing a business is often measured by revenue, new customers and the expansion of operations. These figures are important, but they do not always reveal whether a company is becoming financially stronger. Sales can increase while expenses rise even faster, new customers can bring lower margins than expected, and a business can appear successful while experiencing pressure on its available cash. This is where business profitability analysis becomes an important part of financial management.
For established Australian businesses, understanding profitability means looking beyond the total amount of money coming into the business. It involves examining how revenue is generated, what it costs to deliver products or services, which expenses are consuming margins and which parts of the operation are contributing most effectively to financial performance. Without this understanding, management may continue investing time and money in activities that generate revenue but deliver limited financial value.
Business profitability analysis gives decision-makers a clearer way to understand these relationships. By examining financial information in the context of actual business operations, management can identify opportunities to improve margins, control costs, review pricing and plan growth with greater confidence. The objective is not simply to increase profit for one reporting period, but to build a business that can generate sustainable returns as it grows.
Revenue Growth Does Not Always Mean Better Profitability
Revenue is one of the most visible measures of business performance. When sales increase, it is natural to assume that the business is moving in the right direction. However, revenue alone does not explain how much value the business is retaining after the cost of generating those sales.
Consider a company that wins several new contracts during the year. Its turnover increases, but delivering those contracts requires additional employees, higher supplier costs, more equipment and greater operational support. If the cost of delivering the extra work increases faster than the revenue it generates, the company may be working harder without achieving a corresponding improvement in profitability.
This is one of the first issues that business profitability analysis helps uncover. Rather than treating higher revenue as an automatic sign of success, management can examine how additional sales affect gross profit, operating expenses and the final financial result.
The same principle applies to businesses expanding into new locations, increasing advertising expenditure or adding new products and services. Growth can create genuine opportunities, but its financial value depends on the costs and resources required to achieve it.
A business should therefore evaluate growth not only by how much additional revenue it creates, but also by how much additional profit it contributes and whether that contribution justifies the investment involved.
Business Profitability Analysis Starts With Understanding Your Margins
Profit margins provide a more meaningful view of financial performance than revenue alone because they show how much of each dollar earned remains after particular costs are taken into account.
Gross profit reflects revenue after the direct costs associated with delivering the products or services have been deducted. Operating profit goes further by accounting for operating expenses, while net profit reflects the remaining result after the relevant expenses and other financial items have been considered.
Each measure answers a different question. A business may maintain a reasonable gross margin but experience declining operating profit because payroll, rent, software, insurance or marketing costs have increased. Another business may generate strong operating results but see its final profit affected by financing costs or other expenses.
Effective business profitability analysis examines these figures together rather than relying on one headline number. It helps management identify where financial performance is changing and whether a problem originates in the cost of delivering products and services, the structure of operating expenses or another part of the business.
Margins also need to be interpreted in context. A change in margin is not automatically a sign of poor management. The business may have deliberately entered a new market, introduced a different product mix or invested in capacity for future growth. What matters is understanding why the change occurred, how long it is expected to continue and whether the financial outcome aligns with the business strategy.
Where the Business Is Making Money Matters More Than Ever
A company can be profitable overall while certain parts of its operation are underperforming. This often becomes harder to recognise as the business grows and begins serving different customer groups, selling more products or operating across multiple locations.
Looking at total revenue and total expenses may not reveal which activities are creating the strongest returns. A product that sells in large volumes may require substantial discounts, fulfilment costs or after-sales support. A service that generates less revenue may deliver better margins because it requires fewer resources to complete. A particular customer may provide substantial turnover but require extensive account management and customised work.
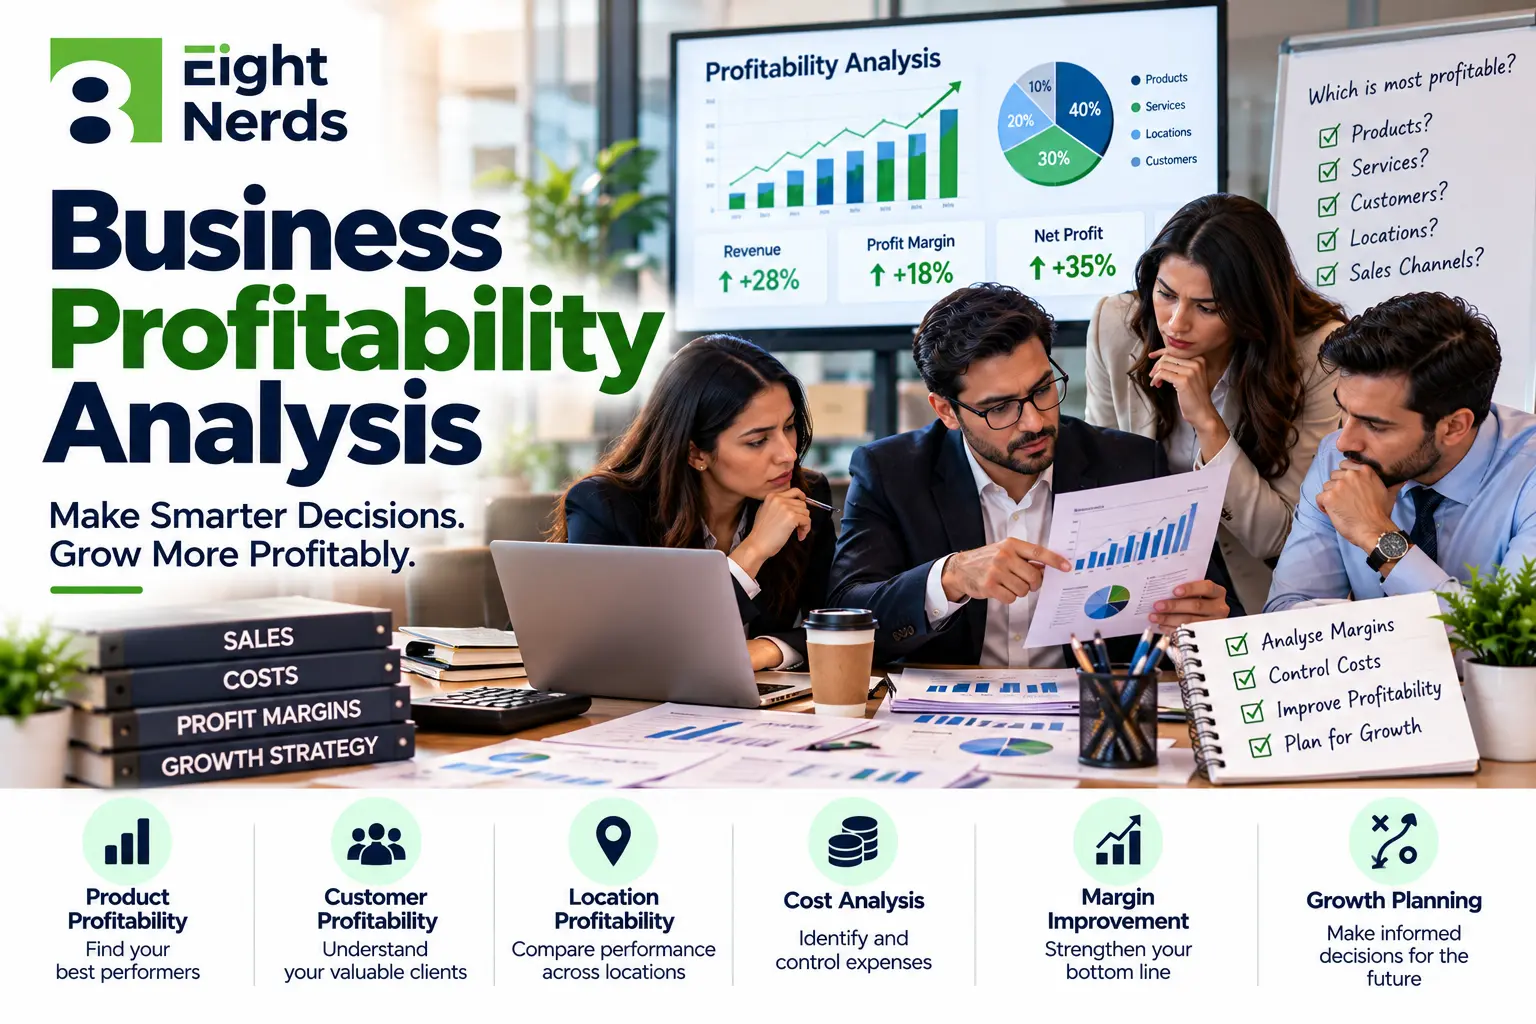
Business profitability analysis can help management examine performance across products, services, customer groups, locations and sales channels. The purpose is to understand how each part of the operation contributes to the overall financial result.
For a professional services company, this could mean comparing the profitability of different service lines or evaluating whether particular projects use more staff time than their fees justify. For a retailer, it may involve examining product margins, supplier pricing and the costs associated with holding stock. For a multi-location company, the analysis could reveal differences in operating costs, sales performance and resource utilisation across locations.
This level of detail supports more informed decisions about where to invest, which activities need improvement and whether certain parts of the business should be restructured. It also prevents management from assuming that every source of revenue contributes equally to financial success.
Rising Costs Can Quietly Reduce Business Profitability
Not all profitability problems come from falling sales. In many cases, revenue remains stable or even increases while the cost of running the business gradually erodes margins.
Supplier prices may rise, wages may increase, delivery charges may change, software subscriptions may accumulate and administrative expenses may expand as the business becomes more complex. Individually, these changes may appear manageable. Together, they can have a meaningful effect on the final financial result.
A structured business profitability analysis examines how these costs are changing in relation to revenue and business activity. It can help identify expenses that are growing disproportionately, operating processes that consume more resources than expected and areas where costs may be reviewed without compromising service quality.
The objective is not to cut every expense. Some expenditure is essential to maintaining quality, supporting employees or creating future growth. Reducing an important investment simply because it increases costs may damage the business rather than improve its financial position.
The more useful approach is to understand the purpose and return associated with significant expenses. Management can then distinguish between costs that support sustainable performance and costs that have increased without delivering a proportionate benefit.
Pricing Decisions Need More Than Competitor Comparisons
Pricing has a direct relationship with profitability, yet many businesses set prices primarily by looking at competitors or responding to customer expectations. While market conditions matter, a price that appears competitive may not leave enough room to cover the actual cost of delivering the product or service.
A business needs a clear understanding of its own cost structure before making important pricing decisions. Direct costs, employee time, supplier charges, overhead allocation, transaction fees and the level of service provided can all influence the financial return generated by a sale.
Business profitability analysis provides a foundation for reviewing these relationships. It can help management evaluate whether existing prices adequately reflect delivery costs, whether discounts are reducing contribution too significantly and whether different customer arrangements produce different financial outcomes.
For example, a company may discover that certain customised projects require considerably more employee time than originally estimated. The issue may not be a lack of demand, but rather a pricing structure that does not adequately account for the work involved.
Similarly, frequent discounts can increase sales volume while reducing the amount earned on each transaction. Understanding this effect helps management make pricing decisions based on the financial consequences rather than on sales performance alone.
Cash Flow and Profitability Must Be Understood Together
Profitability and cash flow are closely connected, but they are not interchangeable. A business can report a profit while experiencing cash shortages because customers have not paid their invoices, inventory has absorbed funds or substantial payments are due before expected receipts arrive.
The reverse situation can also occur. A business may temporarily have a healthy bank balance because it has received advance payments or borrowed funds, even though its underlying operations are not producing sustainable profits.
This distinction is particularly important for businesses experiencing rapid growth. Expansion can require investment in employees, stock, equipment and operating capacity before the financial return becomes available. If these commitments are not planned properly, a profitable business can still face considerable pressure on its working capital.
Business profitability analysis becomes more useful when considered alongside cash-flow forecasting, accounts receivable, supplier payment commitments and working-capital requirements. Together, these provide a clearer picture of both financial performance and the business’s ability to meet its obligations.
Management can then distinguish between a business that needs to improve its margins and one that is profitable but requires better cash-flow planning. That distinction matters because the appropriate response may be completely different in each situation.
Financial Reporting Should Explain What Is Changing
Financial reports are most valuable when they help management understand the reasons behind business performance. A profit and loss statement can show that expenses have increased, but the more important question is which expenses changed, what caused the increase and whether it is likely to continue.
The same applies to revenue and margins. A decline in profitability may result from higher supplier prices, a change in the product mix, lower pricing, increased employee costs or weaker performance in a particular service line. Without examining these underlying factors, management may struggle to identify the right response.
Business profitability analysis brings these figures together to develop a clearer explanation of financial performance. Reviewing current results against previous periods, comparing actual performance with budgets and investigating significant changes can help distinguish temporary variations from patterns that deserve attention.
The reporting process should also reflect the needs of the people making decisions. Business owners may need a clear view of overall profitability and cash availability, while department managers may require more detailed information about operational costs and resource utilisation.
For established companies, this often means moving beyond reports prepared only for year-end or compliance purposes. Regular management reporting gives decision-makers a more current understanding of the business and creates an opportunity to respond before financial issues become more difficult to manage.
Reliable Financial Records Make Profitability Analysis More Useful
The quality of profitability analysis depends heavily on the quality of the underlying financial information.
If bank accounts are not reconciled, expenses are inconsistently categorised, supplier invoices are missing or revenue is recorded incorrectly, the resulting analysis may provide a misleading picture. Even sophisticated reporting tools cannot fully compensate for information that is incomplete or unreliable.
This is why professional bookkeeping remains an important part of financial management. Accurate transaction records, correctly maintained accounts, timely reconciliations and consistent financial processes create the foundation needed to examine business performance with confidence.
For Australian businesses, the underlying records should also reflect relevant GST treatment, payroll transactions and other financial obligations accurately. Where inventory or multiple revenue channels are involved, the accounting process needs to reflect the way those operations actually work.
Business profitability analysis is much more effective when it is supported by reliable bookkeeping and regular financial review. Instead of spending management time correcting inconsistencies, the business can focus on understanding its performance and evaluating potential improvements.
Turning Financial Findings Into Better Business Decisions
Identifying a profitability problem is only the beginning. The real value comes from deciding what action to take and understanding how that action could affect the business.
If a service line generates lower margins than expected, management may need to review pricing, delivery processes or the amount of time allocated to each project. If supplier costs are increasing, the business may need to evaluate purchasing arrangements or consider alternative suppliers. If a particular location consistently underperforms, further investigation may reveal differences in demand, overheads, staffing or operating practices.
Business profitability analysis provides evidence for these decisions, but the numbers should always be considered alongside operational realities. A product with a lower margin may still be important because it attracts customers who purchase other products. A new location may initially deliver weaker financial results while the business builds its customer base. An investment may reduce short-term profitability while supporting a longer-term strategic objective.
The goal is to make decisions with a realistic understanding of their financial consequences. Rather than reacting to a single figure, management can examine the wider situation, compare available options and evaluate whether the expected outcome supports the company’s objectives.
How Often Should a Business Review Profitability?
Profitability should not be reviewed only when the annual accounts are prepared or when management suspects a problem. The appropriate review frequency depends on the size of the business, transaction volumes, operating complexity and how quickly its financial position can change.
For many established businesses, a monthly review provides a useful structure for examining revenue, margins, expenses and overall financial performance. Businesses with multiple locations, high transaction volumes, inventory exposure or rapid changes in costs may benefit from more frequent monitoring of selected indicators.
Business profitability analysis should also be revisited whenever management is considering a significant decision, such as introducing a new product, changing prices, hiring additional employees or expanding into another market. Reviewing the likely financial impact before committing resources can help clarify the risks and expected returns.
The important factor is consistency. A regular process helps management compare financial performance over time, recognise emerging trends and assess whether previous decisions have delivered their intended results.
How Eight Nerds Supports Business Profitability Analysis
For growing Australian businesses, profitability analysis works best when it forms part of a broader financial management process rather than being treated as a one-off reporting exercise. Reliable books, meaningful management reports and a clear understanding of cash flow all contribute to a better view of business performance.
Eight Nerds supports businesses through professional bookkeeping, financial reporting, payroll management, accounts management and Virtual CFO services. These services can help establish a more organised financial foundation and provide management with information that is useful when reviewing margins, monitoring expenses, planning cash requirements and evaluating growth opportunities.
Our approach recognises that businesses need more than a collection of financial figures. They need to understand what those figures reveal about the way the business operates and how financial performance connects with management decisions.
Through business profitability analysis and structured financial support, Eight Nerds helps Australian businesses gain better visibility into their financial position and identify areas that may deserve closer attention. The level of support can be aligned with the company’s operations, financial complexity and reporting requirements, whether it is strengthening existing processes or preparing for its next stage of growth.
Frequently Asked Questions About Business Profitability Analysis
What is business profitability analysis?
Business profitability analysis is the process of examining revenue, costs, margins and other relevant financial information to understand how effectively a business generates profit. It can include reviewing overall performance and comparing profitability across products, services, customers, locations or sales channels.
Why is business profitability analysis important for growing companies?
As companies grow, their revenue, operating expenses and financial commitments often become more complex. Business profitability analysis helps management understand whether growth is improving financial performance, identify areas where margins are under pressure and evaluate where resources may be used more effectively.
What financial information is needed for profitability analysis?
The process generally uses reliable revenue and expense records, cost information, financial statements and relevant management reports. Depending on the business, it may also require information about inventory, employee costs, pricing, customer groups, products, service lines or different operating locations.
How is profitability different from cash flow?
Profitability measures the financial result generated by business activities, while cash flow reflects the movement of money into and out of the business. A profitable company can experience cash shortages when payments are delayed or funds are committed to inventory and other expenses before cash is received.
Can profitability analysis help with pricing decisions?
Yes. Business profitability analysis can help identify whether prices adequately cover the costs involved in delivering products or services. It can also help management understand the effect of discounts, changes in supplier costs and variations in customer or product profitability.
Can a Virtual CFO help with business profitability analysis?
A Virtual CFO can help interpret financial reports, review profitability trends, examine operating costs and connect financial findings with budgeting, forecasting and business decisions. The value depends on the business’s requirements and the quality of the underlying financial records.
Make Business Profitability Analysis Part of Your Growth Strategy
A growing business needs to understand more than how much it sells. It needs to know which activities generate sustainable returns, where costs are affecting margins and how future decisions may influence financial performance.
Business profitability analysis provides a structured way to examine these questions. When supported by accurate bookkeeping, meaningful reporting and regular financial review, it can help management identify opportunities, understand risks and make more informed decisions about the direction of the business.
For established Australian businesses, profitability should be treated as an ongoing management priority rather than a figure reviewed only at year-end. Eight Nerds combines professional bookkeeping and financial support with Virtual CFO services to help businesses build a clearer picture of their financial performance.
Speak with Eight Nerds about business profitability analysis, financial reporting and Virtual CFO support tailored to your business.
- Buying an existing Business? Financial Due Diligence – What to Check Before Buying a company in Australia
- What is Business Expense Management ? How Australian Businesses Can Control Rising Costs
- Revenue vs Profit | How Bookkeeping Helps You Understand What Your Business Really Earns | Eight Nerds
- Business Profitability Analysis for Growing Australian Businesses | Eight Nerds
- Why to Hire a Virtual CFO for a Growing Australian Business
One thought on “Business Profitability Analysis for Growing Australian Businesses | Eight Nerds”
Add a Comment Cancel reply
All Categories
Recent Posts
What is Business Expense Management ? How Australian Businesses Can Control Rising Costs
[…] costs continue to rise without a clear understanding of how they affect profitability. This is where business expense management becomes an important part of running a financially healthy […]